The crypto regulations in Congress are still pending after the rejection of a procedural motion in the Senate on September 15, which could have paved the way for the passage of the Digital Asset Market Clarity Act, H.R. 3633. The vote of 49-50 meant the proposed provisions relating to the involvement of banks in crypto were still pending.
The Senate Banking Committee’s version of the bill includes provisions that would clarify how financial holding companies, national banks, state banks and certain credit unions could use digital assets and blockchain technology for activities they are already permitted to conduct. These activities include payments, lending, custody and trading.
According to an analysis by the Congressional Research Service on Sept. 30, the Senate version of the bill would create 11 types of acceptable activities related to cryptocurrencies that banking institutions and credit unions can undertake. These provisions will not necessitate financial institutions to provide those services, as the applicable regulations will still apply.
Crypto Regulations for Congress Covering Banks’ Blockchain Activities
The bank provisions revolve around how existing financial authorities can regulate blockchain-powered means of undertaking activities that are authorized by banking law.
That distinction extends the discussion beyond cryptocurrency trading alone. Blockchain infrastructure can be used for transaction records, settlement and tokenized financial assets, according to the information provided in the legislation’s banking provisions.
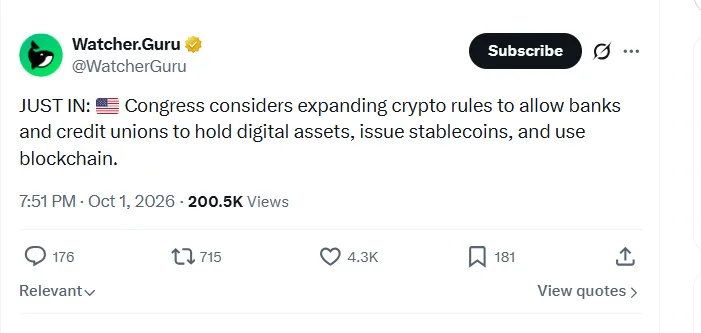
Source: Watcher.Guru
Financial institutions are already investigating blockchain-based settlement systems. According to Reuters news agency in September, leading European banks are using a blockchain-based settlement system, which is created by the European Central Bank.
The proposed congressional framework would therefore establish a clearer statutory basis for certain activities while leaving institutions subject to existing regulatory requirements. The Sept. 15 Senate vote, however, means those proposed changes have not become law.
Stablecoin Rewards Remain a Central Banking Issue
Stablecoins are another major component of the debate. DefiLlama estimates that the market capitalization of stablecoins exceeds $305 billion, with USDT representing 60%.
Currently, the United States has a federal structure for regulating payment stablecoins through the enactment of the GENIUS Act in July 2025. The act outlines regulations for eligible issuers of payment stablecoins in terms of reserves, redemption, disclosure, and regulation.
Moreover, the Office of the Comptroller of the Currency has issued proposed rules regarding the reserve assets, custody, risk management, auditing, and supervision of the issuer.
CLARITY Act discussions thus revolve around how stablecoins work within the larger framework of the financial sector and not creating federal oversight of stablecoins right at the outset.
One disputed issue is whether stablecoin users should receive interest-like payments or rewards. A May 12 Senate Banking Committee section-by-section document proposed restricting covered digital-asset service providers and affiliates from paying passive, deposit-like interest or yield on payment stablecoin balances while permitting certain transaction-based rewards.
The banking industry groups had cautioned that such reforms would lure deposits out of banks. The American Bankers Association and other industry groups said that such reforms could result in less deposits for lending to individual households, small businesses, and communities.
Credit Unions: Part of Proposed Congress Crypto Framework
The credit unions were not left out in the proposed framework. Credit unions were listed among financial institutions that can use digital assets and blockchain technology in the Senate Banking Committee legislation.
The NCUA has stated that federally chartered credit unions are not presently authorized to custody crypto-assets and other digital assets. State-chartered credit unions may have some authority pursuant to the laws of individual states, while the custody of digital assets via third-party custodians does not fall under the NCUA Share Insurance Fund.
The regulator was also readying itself for regulating stablecoins. According to the chairman, the NCUA issued a proposed rule in February 2026 on the licensing of payment stablecoin issuers by federally insured credit unions and their subsidiaries.
What Happens After the Senate Vote?
The September 15 procedural defeat did not alter any existing banking powers nor create new ones but left the proposed market structure changes unsettled.
The regulatory agencies have been working within their existing powers. The CFTC sent its proposed crypto-market regulation rule to the White House after the Senate’s vote, whereas the SEC has been working on its digital asset regulations using its existing powers, according to CoinDesk.
The OCC and Federal Reserve are also crafting regulations related to the GENIUS Act. Their efforts will impact how permitted stablecoin issuers conduct themselves within the existing federal framework as Congress contemplates further market structure legislation.
Takeaways from This Article
- Congress crypto regulations may define permitted digital asset and blockchain activities by banks and some credit unions.
- Stablecoin rewards remain disputed because banking groups have raised concerns about competition for deposits.
- The Sept. 15 Senate vote left H.R. 3633 unresolved while regulators continue work under existing authority.